Buying
Buying an Owner-Occupied Commercial Building
An owner-user is buying a place to operate, and also buying a property that will have to be sold or leased later. The business fit comes first. The investment math comes right after it.
Quick answer
Test location, size, expansion, parking, loading, and power against how the company actually works. Then compare occupancy cash, the down payment, and the financing with the lease you would otherwise sign. Keep the comparison pre-tax, and plan the exit before you close.
Key takeaways
- The building has to work for the operation on a real move-in date.
- Occupancy cost includes debt, repairs, and reserves, not just a comparison with rent.
- Owning is less flexible. The exit is a future sale or a lease to someone else.
- Read the lease-versus-buy article before you assume buying is the goal.
Start with the operation
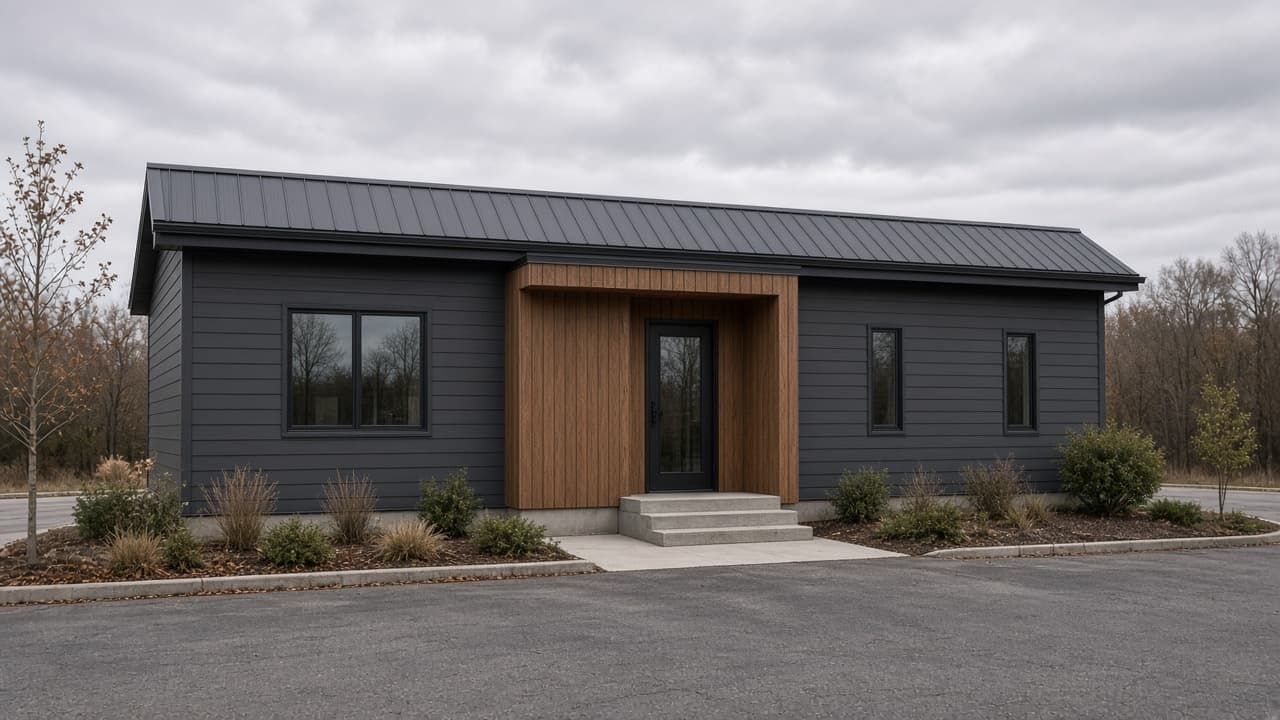
List what the business does in the space on a normal week. Customers, employees, inventory, vehicles, and equipment each make a demand. A building that photographs well and fails that list is the wrong building. The owner-user page is the property-type view. This article is the buying sequence.
Location is an operating fact. Where do employees live, where do customers come from, and which suppliers need to reach the dock? A west Omaha site and a north Lincoln site solve different problems. Do not pick a metro and then ignore the block. Lease or buy is worth reading if the company is still unsure it should be in this location five years from now.
Size, expansion, parking, loading, and power
Size cuts both ways. Too little space means another move. Too much space means you carry vacant area the business does not need, unless you have a real plan to lease the extra. Leasing a portion changes the building into a small investment as well as a workplace. Lenders may treat that mix differently. Ask them. Do not assume the extra suite is free income.
Expansion room only counts if zoning, setbacks, and utilities allow the addition. Parking has to hold staff and visitors, and the code may require a count you should confirm with the city. Loading and truck access matter if you ship anything. Power matters if equipment is the business. Ask an electrician or the utility what service is in the building.
| Line | Lease path | Buy path |
|---|---|---|
| Cash at the start | Deposit and moving costs | $300,000 cash to close on a $1,200,000 price, before repairs |
| Recurring occupancy cash | $8,000 a month in rent, or $96,000 a year | Debt service from your term sheet, plus owner-paid expenses |
| Repairs | Whatever the lease assigns to you | Roof, systems, and reserves you now own |
| Way out | Leave when the term allows | Sell, lease, or keep paying |
The $8,000 and the $1,200,000 are round teaching numbers. They are not Omaha rents and not Lincoln prices. Put a real loan into the loan payment calculator and a real cash split into the equity calculator. The lease versus buy calculator can line up the cash paths. It will not decide for you, and it is not a tax model.
Financing and occupancy cost
Owner-user financing looks at the property and the business. Some SBA programs are aimed at owner-users. A lender applies eligibility, occupancy, and use-of-proceeds rules to the borrower and the property. Conventional loans are a different conversation. How financing works keeps the terms straight: rate, amortization, maturity, and recourse.
Compare the payment with the rent you would otherwise pay, then add the expenses the landlord used to carry. Taxes, insurance, and repairs do not disappear because you bought the building. If you borrow, look at coverage with the DSCR calculator using property income only if that is what the lender is using. Some owner-user loans look at the business as well. The lender defines that.
Flexibility and the exit
A lease lets you leave when the term says you can. A purchase means you own the vacancy if the company outgrows the building, shrinks, or needs a different part of the metro. Flexibility has a price. So does control. Name the holding period you actually believe, and ask what the building is worth if you must sell it then, with your improvements and with a vacant suite.
The exit buyer may be another owner-user or an investor who wants a lease. Those are different sales. An improvement that only your business can use may cost more than the next buyer will pay. Talk with your accountant about taxes before you model a savings. This article stays pre-tax on purpose. When you are ready to test a specific Omaha or Lincoln building, the buy page is the path.
Questions people ask
Should a business always buy if it can?
No. Buying fits a company that knows its location, can spare the cash, and can live with a building it must later sell or lease. Leasing fits uncertainty. The lease or buy article frames that choice.
Can I live off the extra space I do not need?
Only if someone leases it on terms you can enforce. Vacant area is an expense until then. Lenders may not count hopeful rent. Label any lease-up as a forecast.
Is SBA financing automatic for owner-users?
No. Some SBA programs are built for owner-users, and a lender still has to approve the borrower, the business, and the property.
What if I only need the building for three years?
Then the exit is the main underwriting problem. Transaction costs, a short hold, and the risk of selling vacant can erase the occupancy savings. Run that case before you sign.
Written by Bryan Robinson, a Professional Sales Agent with NHS Commercial, licensed in nebraska.
Want help evaluating a commercial property?
Call or text Bryan at 402-521-3000 to talk through a specific property.
Bryan Robinson
NHS Commercial
Professional Sales Agent | Licensed in Nebraska